Why We Bought Our BTL Through a Limited Company – And How It Came Together in Two Weeks
Why buy a BTL through a limited company rather than in your own name? I did not set out to buy a property through a limited company. I did not even set out to buy a property. What happened was closer to how most of my decisions work – a slow build of curiosity that tipped into action faster than anyone around me expected.
At the time I was three months into maternity leave. I had closed my street food business because three months off was not going to be enough, and I knew I wanted to be at home with my son for at least two years. I had no active income. What I did have was time to read, think and research – and a growing conviction that property investment through a company structure was the most tax-efficient way to build something for the long term.
How the idea built
It started the way these things usually do for me. Reading the Financial Times over coffee, articles in the Guardian, conversations with friends who were further along in property, Instagram accounts I follow for finance content. Nothing structured. Just absorbing.
Then something clicked. I started reading more deliberately about limited company BTL structures – corporation tax rates versus personal income tax on rental income, the ability to offset mortgage interest fully against profits, the flexibility of retaining earnings in the company rather than extracting them immediately. The numbers made sense in a way that buying personally did not, especially for higher-rate taxpayers.
Once I had the idea in my head, the tunnel vision kicked in. I started researching Bristol specifically – yields, areas, property types, transport links. I was not consciously planning to buy. I was just answering questions to see if the idea was viable.
From holiday to acquisitions trip
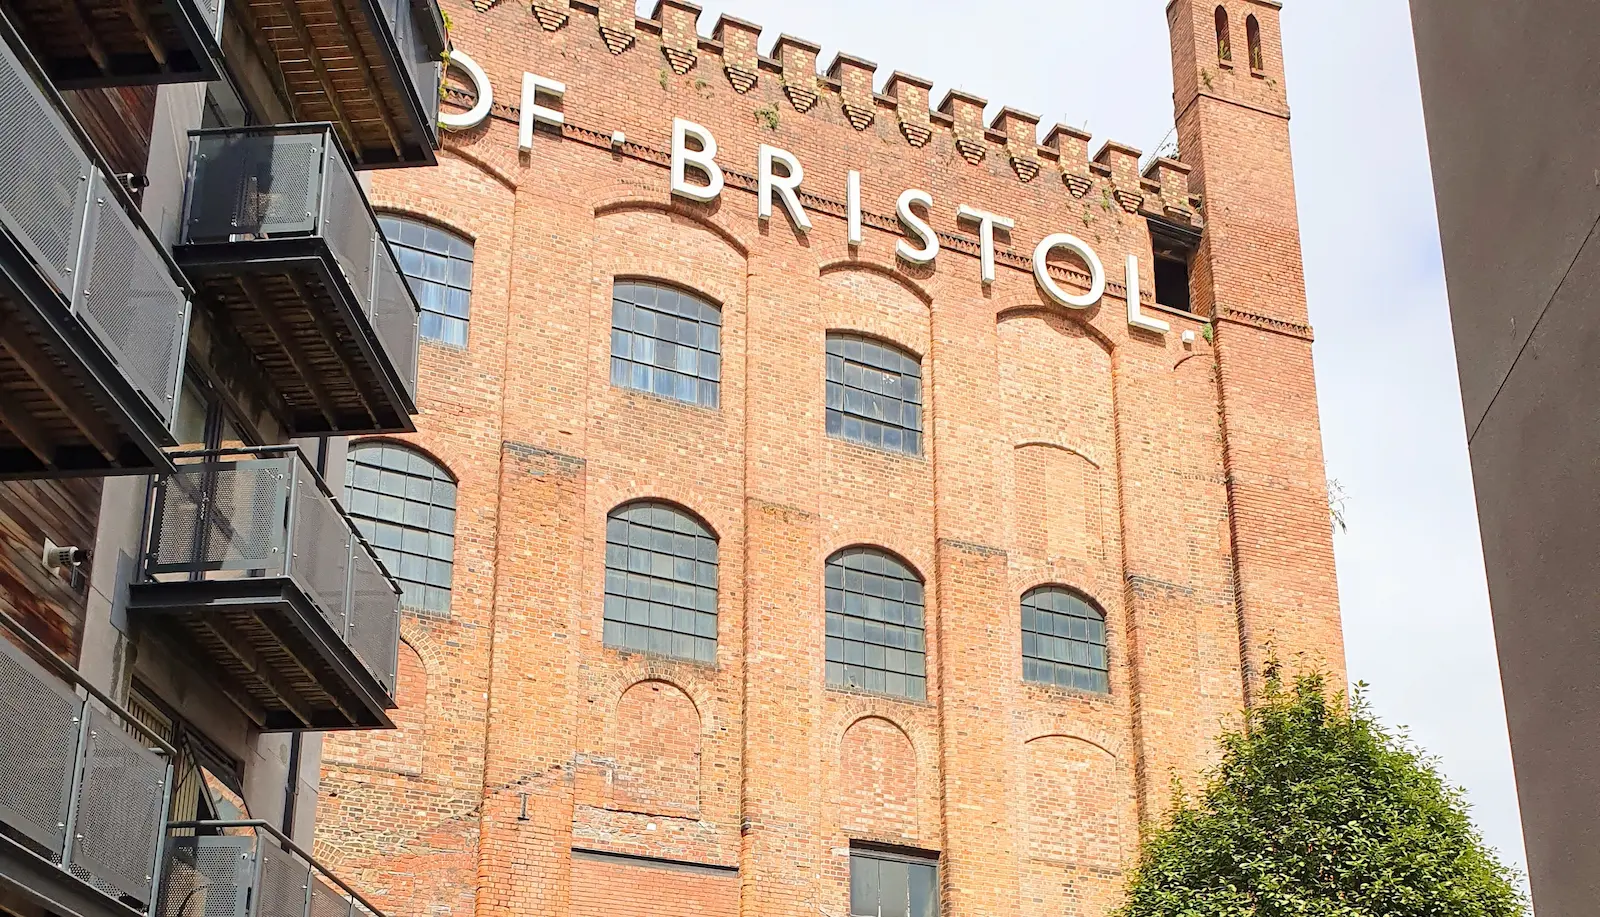
A friend was going on holiday and offered us their house in Bristol for a couple of weeks. Originally it was just a trip – a change of scenery with a four month old baby. But by the time we arrived, I had booked viewings. As many as I could fit in a day, mortgage meetings squeezed in around nap times, and a clear goal: find a property that worked on the numbers and get an offer accepted.
The company did not even exist yet.
We formed it on the sofa of our friend’s house. It took about fifteen minutes on Companies House. My husband went down as sole director and 100% shareholder. The reasoning was practical – I had no active income having just closed my business, and I already had a mortgage on my own property in London. Lenders needed someone with employment income to provide the personal guarantee, and having two mortgages across the application would have reduced what we could borrow. Keeping it simple and in his name meant we could get real BTL mortgage quotes based on actual circumstances, quickly.
That was the entire setup. Sole director, sole shareholder, formed in fifteen minutes to unlock the next step. No accountant involved at that stage, no legal advice on structure. Just enough to start getting quotes and making offers.
Why a limited company and not personal ownership
The decision came down to tax.
I already had rental income from my London property – enough to keep me in the basic-rate tax band as my only personal income. If we had bought Bristol personally, that second rental income would have stacked on top and pushed me into higher-rate territory.
That would have been painful for two reasons. First, the portion above the threshold would be taxed at 40%. Second, personal landlords can no longer fully offset mortgage interest against rental income – the rules changed in 2017 and the relief is now far less generous. So I would have been paying higher-rate tax on income that was largely being absorbed by mortgage payments.
Buying through a limited company kept the two income streams completely separate. The Bristol rental income never touches my personal tax return. It sits in the company where mortgage interest is still fully deductible as a business expense, and corporation tax is lower than what I would have paid personally. I only pay personal tax when I choose to take money out of the company, which gives me control over the timing.
The limited company did not just save tax on the Bristol property. It protected my entire personal tax position by keeping me below the higher-rate threshold.
What the setup actually looks like now
The company structure has changed since that evening on the sofa. I have since been added as a director, by myself, including a few admin mistakes along the way.
Day to day, the company runs simply. Rental income goes into a dedicated business bank account. Company expenses come out of the same account. I do the bookkeeping myself using Xero, which handles the Making Tax Digital submissions to HMRC. We file annual accounts and a corporation tax return, which I also handle directly rather than using an accountant.
The running costs are modest – the Xero subscription and the annual Companies House confirmation statement. The property management is done by me remotely, which keeps overheads low and it means I’ve keep a close eye on the actual running costs over the past three years.
What I would tell someone considering this
The limited company route is not for everyone. It adds admin – a company to maintain, accounts to file, and a different tax structure to understand. If you are a basic-rate taxpayer with one property and a small mortgage, buying personally might be simpler and work out similarly.
But if you already have rental income or employment income that puts you near the higher-rate threshold, or if you are planning to build a portfolio over time, the company structure is worth serious consideration. The tax treatment of mortgage interest alone can make a significant difference to whether a property is genuinely profitable or just looks profitable on paper. It was only when doing the annual accounts that we understood how thin the surplus would be once the carried forward losses ran out, and what that means for the company’s ability to cover its own tax bill.
The most important thing I learned was that the setup does not need to be perfect from day one. We formed the company in fifteen minutes to get moving. The structure evolved as our circumstances changed – new directors, adjusted shareholdings, product transfers on the mortgage. Getting started mattered more than getting it right immediately, as long as I was prepared to fix things along the way. What the company contributes to our overall family net worth is a separate question – one I now track in a dedicated family wealth tracker.
And that willingness to fix things turned out to be important. Because I definitely got some of it wrong.
This article reflects my personal experience and is not financial or tax advice. Limited company structures have implications for mortgage eligibility, tax obligations, and legal responsibilities. Speak to a qualified accountant or tax adviser before making decisions about property ownership structures.