What It Actually Costs to Run a BTL Through a Limited Company – Three Years of Real Numbers
BTL limited company running costs are not what most people expect. I have been tracking every penny that flows through our limited company property business since we formed it. Three years of bank statements, every transaction categorised, nothing estimated. What follows is the full picture of what it actually costs to buy and run a leasehold flat in Bristol through a UK limited company – from setup to steady state.
I am not going to pretend the numbers are exciting. This is a property that covers its costs, builds equity slowly, and sits quietly inside a company structure that protects my personal tax position. That is exactly what it is supposed to do.
Why this type of property
We bought a two-bed leasehold flat that needed cosmetic work but nothing structural. That was a deliberate choice.
We could have gone for a fixer-upper at a lower purchase price and forced the value up through renovation. On paper that looks smarter. In reality, we had a six month old baby, no financial cushion to absorb building delays or cost overruns, and no appetite for the stress and uncertainty of a full refurbishment in a market where build costs were unpredictable.
Instead we chose a flat that I could get ready myself in a couple of weeks with minimal professional help. The bathroom fixtures needed refreshing, both toilets were broken, the kitchen cabinet doors needed stripping back to neutral, door frames needed fixing, the front door needed new locks, the kitchen counter needed repairing, and the electrics needed checking. A builder and electrician handled the bigger jobs. I did everything else.
We completed on 17th February and the first tenants moved in on 1st April.
→ How I find tenants without agents here.
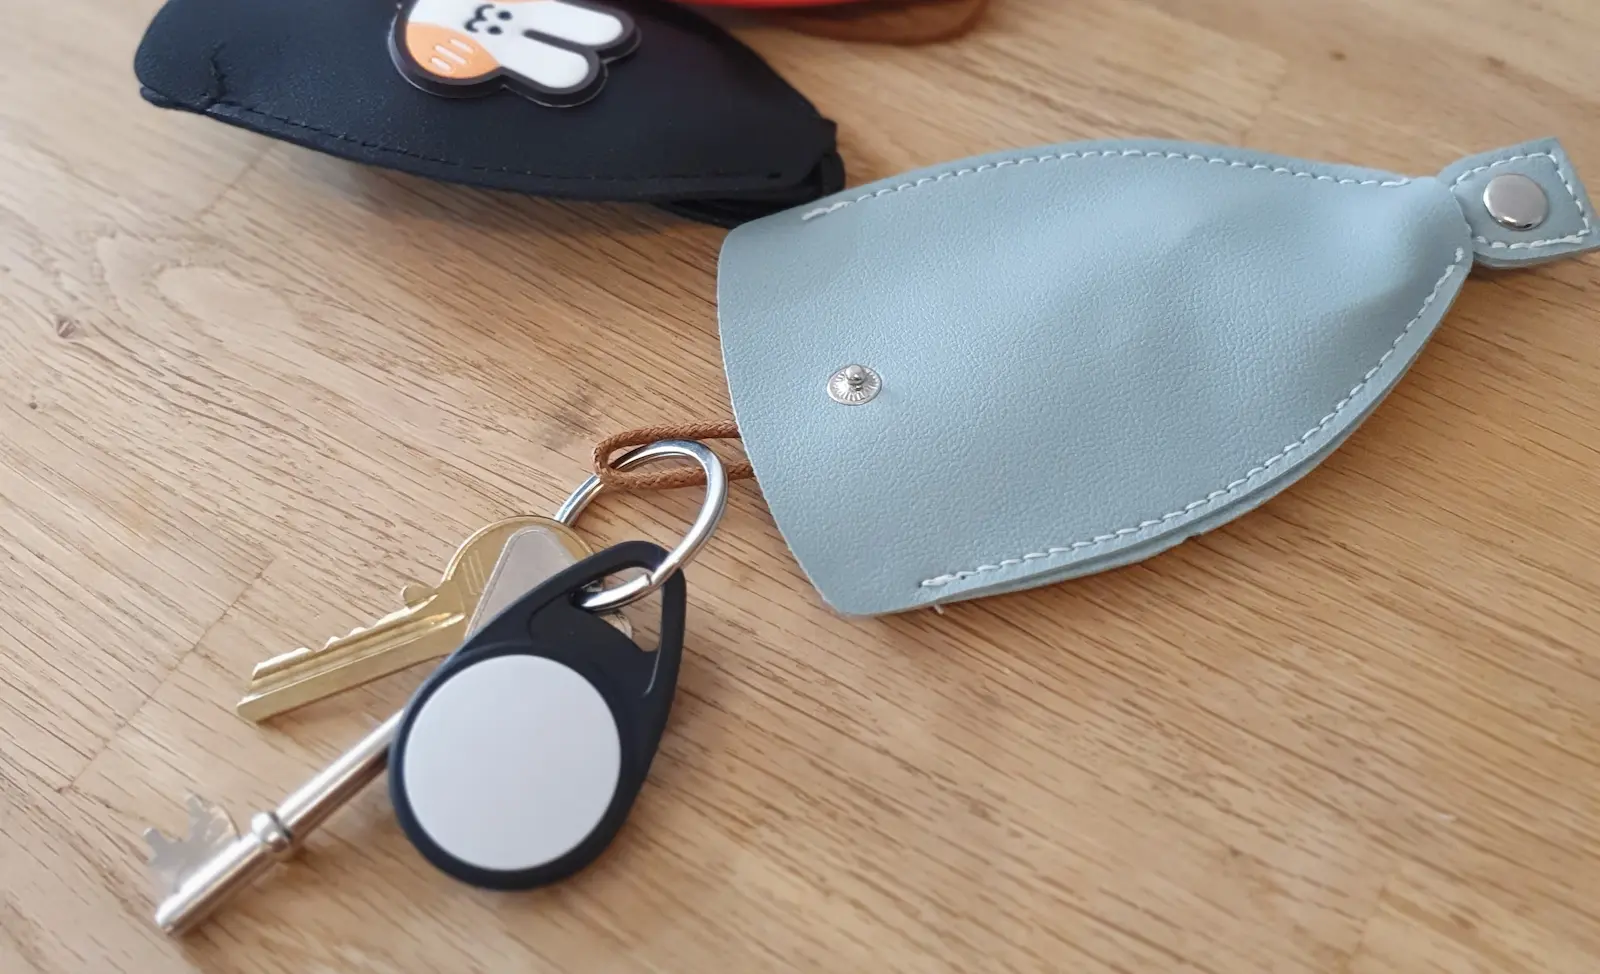
On handover day, they called because no Ubers would accept them with all their belongings. I drove over, we loaded everything up, and drove back to the flat together. I had bought them each a little keyring – the kind that pulls the keys into a small pouch, each with a different colour and design. I just wanted them to know I cared and that I would do my best for them. As I was driving off after getting them settled, one of them came running down the stairs with a fistful of individually wrapped Indian chocolates and a huge thank you. The relationship between us has been one of kindness and mutual respect from that day.
That is what I mean when I say these are people’s homes. The numbers matter, but they are not the whole story.
→ How I manage tenants day to day here.
The trade-off with a leasehold flat is the service charge. You pay it every six months and you do not control what it costs. But in return, the building’s structure, roof, communal areas and major repairs are not your problem. For someone managing a property remotely with limited time, that trade-off is worth it. The income is modest, but the risk was low and the timeline was within my control.
A note on the mortgage
We fixed for two years rather than five. That was a deliberate decision. A shorter fix means we are exposed to rate movements sooner, which is a mild gamble – but it also means that if rates drop, we benefit more quickly rather than being locked into a higher rate for years. So far that approach has worked for us, though it does mean periodically going through the process of securing a new fix.
Year one – the setup year (tax year 23/24)
The company was formed partway through this tax year, so the numbers only cover a partial period. I wrote about how and why we formed the company here including the admin mistakes when I added myself as director here.
Money in: £4,400 in rental income from three months of tenancy.
Money out: £4,191 in actual costs. One mortgage payment of £1,396. About £1,114 in services – the builder and electrician sorting out the issues the flat needed. Furniture and fittings cost £1,035, almost all sourced second hand on eBay and collected and installed by me. Brand new mattresses were the only exception. Everything else came from eBay listings and a combination of my own effort and the kindness of two friends in Bristol who gave up an afternoon to help me get the sofa up the stairs. People tend to be generous if you ask.
Travel came to £361. The rest was small costs: supplies, meals on work days, bills.
The tenancy deposit of £2,200 was also registered with TDS during this period. That is not a cost to the company – it is the tenant’s money held as security against damages and is returned at the end of the tenancy. It ties up cash flow temporarily but does not appear on the profit and loss.
Net result: +£209. Roughly breakeven in a partial setup year, which is about as good as you can hope for when you are furnishing a flat and paying tradespeople before full income starts.
We also transferred £4,011 of personal funds into the company during this period to cover the cash flow gap while rent was not yet coming in.
Year two – the first full year (tax year 24/25)
This is where the picture becomes clearer.
Money in: £26,400. Twelve months of rent at £2,200 per month, consistent throughout the year.
Money out: £23,320.
The mortgage is the dominant cost at £14,629 for the year, roughly £1,219 per month.
Bills came to £3,388 – electricity, water, and broadband. The tenants pay council tax themselves.
Service charge and ground rent together totalled £2,304, paid every six months. I should note that this figure was inaccurately low. The management company at the time had been mishandling the collection of service charges, which meant we were underpaying. They were later replaced by a new management company, and the corrected figures show up in year three.
Services – maintenance and repairs – cost £790 across 16 transactions. Most of my regular tradespeople were found through Airtasker originally and have become reliable contacts over time.
Other running costs covered travel to Bristol, general expenses, small equipment and inventory replacements, and came to about £2,209 combined.
Net result: +£3,080. About £257 per month. Not life-changing, but the mortgage is being paid by tenants and equity is building quietly.
Year three – current year (tax year 25/26)
Money in: £26,513. Same rental income plus small refunds.
Money out: £25,623.
The mortgage stayed identical at £14,629.
Bills were similar at £3,395.
The service charge and ground rent increased to £3,893 combined. The new management company is now collecting accurately after replacing the previous one, which had persistently mishandled charges. This is the corrected figure, and it is the real baseline going forward. With leasehold property, the service charge is the one cost you do not control and it is the line I watch most carefully.
Services and repairs together came to £1,566, higher than last year – a blocked toilet, some new light fixtures, and general maintenance.
Software was £50 for Xero. The Companies House annual confirmation statement was £35. There was a £150 mortgage product transfer fee. Travel and other running costs made up the remainder.
Net result: +£889. Still positive, but tighter than year two. The service charge correction absorbed most of the difference. Year two was artificially good because we were being undercharged – the real steady state is probably somewhere between the two years.
What the numbers actually tell you
Across three years, the property has moved from breakeven to a consistent surplus:
Year one (partial): +£209 Year two: +£3,080 Year three: +£889 Cumulative net: +£4,178
These figures reflect the actual cash flowing through the company bank account – what came in and what went out. The accounting picture looks different. When I reconcile the books through Xero each year, the company has not yet made a taxable profit. Setup costs, allowances, and the way mortgage payments are treated in the accounts all affect that calculation. The capital repayment portion of the mortgage, for example, is not a deductible expense even though it leaves the bank account every month. Losses have been carried forward each year, and we have not paid any corporation tax in three years of operation. I do not expect to for the current year either. When those losses finally run out, the picture changes. What happens to a BTL limited company at that point is worth understanding before it arrives rather than after.
That is worth understanding if you are considering this route. A property can be cash-flow positive, covering its mortgage and all running costs from rental income, while the company shows no taxable profit on paper. That is not a loophole – it is how the accounting works in the early years of a leveraged property held in a company. Those carried-forward losses will reduce the tax bill when the company does eventually become profitable in accounting terms.
The mortgage is being paid by tenants. Every month, equity in the property increases. The company structure means the rental income does not push my personal earnings into the higher tax bracket. And the property sits inside a vehicle that can hold further investments over time without changing my personal tax position.
The annual running costs once the property was established – stripping out the mortgage and one-off setup costs – come to roughly £8,700. That covers bills, service charge, ground rent, maintenance, travel, software and other expenses. Against £26,400 in rent, that leaves about £17,700 to service the mortgage and continue building equity.
What I would want someone to know
The numbers are not dramatic. This is not a get-rich-quick story and I would not trust anyone who told you buy-to-let through a limited company was one.
What it is, is a structure that works quietly in the background. Tenants pay rent, costs are covered, equity builds, and my personal tax position stays protected. The admin is modest – a few hours a month at most – and the running costs are predictable outside of the service charge. The company picture and the personal picture are separate – I track how they fit together in my family net worth tracker.
If you are considering this route, think carefully about what kind of property matches your actual circumstances, not just the numbers on a spreadsheet. We chose low risk, fast turnaround, and controllable costs over higher potential returns with higher uncertainty. That decision has meant three years of a property that runs without drama, managed remotely, while I focus on raising my son and building other projects.
The setup period will feel tight on cash. The first full year will feel like a relief. After that, it becomes routine. And routine, when it comes to property, is exactly what you want.
This article reflects my personal experience and real financial data. It is not financial or tax advice. Property investment involves risk and individual circumstances vary. Speak to a qualified accountant or financial adviser before making investment decisions.